

Pick a stock or ETF and an options strategy, say when to open and close each trade, and see how it would have done, trade by trade, on our own end-of-day option prices going back to 2015. Then save it, and track the strategy from today on in a portfolio.
The options backtester is included with Market Chameleon Premium.
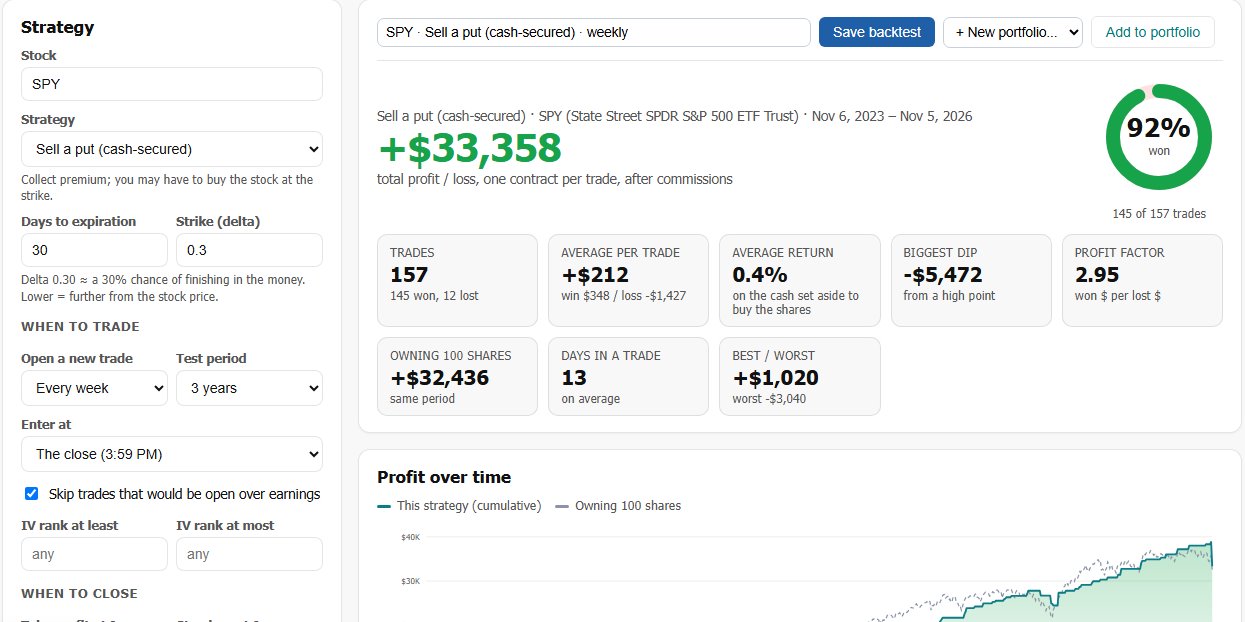
Choose the days to expiration and the strike by delta (for example a 0.30-delta put about a month out), and the wing distance for spreads and iron condors.
Run a backtest at the midpoint between the bid and the ask, or with real fills: buy at the ask and sell at the bid, only in options with a tradable market (a bid and an ask above zero and a spread no wider than $0.10 or 25% of the midpoint) and enough liquidity (open interest of 100 or more, or volume of 10 or more). With real fills an exit waits for a day the option can actually be traded, and commissions come off every trade - so a strategy that only works on paper shows up as one.
Save any backtest, then add it to a portfolio. From the next trading day the portfolio runs the same rules forward on end-of-day prices with real fills, next to the backtest's own record, so you can see whether a strategy keeps doing what the history said. Market Chameleon keeps example portfolios too, from income strategies to earnings plays.
An options backtester replays an options strategy on past market data to show how it would have done: every trade it would have opened and closed, the profit or loss of each, and the total over the test period. Market Chameleon's backtester does this for U.S. stocks and ETFs using our own historical option prices.
End-of-day option prices - bid, ask and closing prices for every listed option - for U.S. stocks and ETFs since January 2015, together with daily stock prices, earnings dates and our record of large option trades. Trades can be entered at the open, at midday or at the close.
Two ways. At the midpoint between the bid and the ask, or with real fills: buying at the ask and selling at the bid, only in options with a tradable market (a bid and an ask above zero and a spread no wider than $0.10 or 25% of the midpoint) and enough liquidity (open interest of 100 or more, or volume of 10 or more). With real fills an exit waits for a day the option can actually be traded. Commissions are taken off every trade.
Sell a put (cash-secured); Covered call; Buy a call; Buy a put; Bull put spread (credit); Bear call spread (credit); Bull call spread (debit); Bear put spread (debit); Iron condor; Short strangle; Long straddle. Choose the days to expiration and the strike by delta, plus the wing distance for spreads and iron condors.
Yes. Besides opening a trade every week or every month, you can open one a set number of days before each earnings date and close it after, or follow the day's largest option trades - for example every $1 million call purchase in a stock - and see how copying them would have worked.
Yes. Save a backtest, then add it to a portfolio. From the next trading day the portfolio runs the same rules forward on end-of-day prices with real fills, so you can compare how the strategy does from here on with what the backtest showed. Market Chameleon keeps example portfolios of its own.
The backtester is included with Market Chameleon Premium. The guide to how it works, with worked examples, is free for everyone.
No. Backtest and portfolio results are hypothetical: no trades were placed and no money was invested, and past results, actual or hypothetical, do not guarantee future results. They are for research and education, not a recommendation to buy or sell any security.
The options backtester, its portfolios and every Premium report and screener are included with Market Chameleon Premium. Read the guide to the backtester to see exactly how it works, with worked examples.
Important: hypothetical results, not investment advice. The backtests and portfolios on these pages are hypothetical. They show what a set of rules would have done on historical and end-of-day option prices; no trades were placed and no money was invested. Portfolios apply the same rules going forward from the day they were added, using end-of-day prices; they are not real accounts and do not reflect actual trades.
Hypothetical or simulated performance results have certain limitations. Unlike an actual performance record, simulated results do not represent actual trading. Since the trades have not been executed, the results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown. Results reflect the fill and commission assumptions stated with each test and may not reflect taxes, margin requirements, early assignment, dividends or other costs.
Stock and option trading involves risk that may not be suitable for all investors. Options involve risk and are not suitable for all investors; before trading options, read Characteristics and Risks of Standardized Options.
This information is provided for informational and educational purposes only and should not be construed as investment advice, or as a recommendation to buy or sell any security or to follow any strategy or portfolio. Neither Market Chameleon nor any other party makes warranties regarding results from its usage. Past performance, actual or hypothetical, does not guarantee future results. Please consult a financial advisor before executing any trades.