

Diagonal Put Spread
A diagonal put spread buys a longer-dated put and sells a nearer-dated put at a lower strike, usually for a net debit. It does best if the stock drifts down to the short strike by the near expiration, and with the long put at the higher strike the most it can lose is the debit.
What is a diagonal put spread?
A diagonal put spread buys a put with a later expiration and sells a put with a nearer expiration at a different strike. In the usual version the put bought has the higher strike and the put sold has the lower strike, so the trade costs a net debit. It is the put-side mirror of the diagonal call spread: a mildly bearish, time-decay trade that does best if the stock drifts down to the short strike by the near expiration.
After the near put expires you still own the later put, and you can sell another near-term put against it. Because the long put sits at the higher strike with more time left, it covers the short put the whole way down.
| Version | Legs | Opened for | Most it can lose |
|---|---|---|---|
| Usual diagonal put spread | Buy a later-dated put at strike B, sell a nearer-dated put at a lower strike A | A debit | The debit |
| Reverse diagonal (our Strategy Benchmarks index) | Buy a near-dated at-the-money put, sell a later-dated put 5% lower | A small debit or credit | Hard to cap before the near expiration; after it, if the later put is kept, up to its strike minus the net premium, with the stock at zero |
How a diagonal put spread pays off
For the usual version - long the later put at strike B, short the nearer put at strike A, with A below B:
- Net cost. The later put's premium minus the nearer put's premium: a debit.
- At the near expiration. The short put expires worthless if the stock is above A, and you keep the later put, worth whatever the market pays for it then. Its value depends on the stock price, the time left and implied volatility, so the gain and breakeven come from valuing that put, not from a fixed formula.
- Best case. The stock sits right at A as the near put expires.
- Most it can lose: the debit. If the stock rises far, both puts lose their value and the loss approaches the debit. On a fall, the long put at the higher strike is always worth at least what the short put owes.
- On a big drop. Both puts go deep in the money and the spread is worth at least the distance between the strikes (B minus A), since the long put can be exercised. You make money if the debit is less than that distance.
- Implied volatility. The later put has more vega, so a rise in implied volatility helps and a fall hurts.
The reverse version and its risk
Buying the near-dated at-the-money put and selling a later-dated put 5% lower - the structure our Option Strategy Benchmarks track - loses most if the stock is at or above the long strike at the near expiration: the long put expires worthless while the later short put keeps its time value. It is short vega. Once the near put expires, the later put you sold is uncovered: kept open, it is a naked short put, and if the stock falls to zero it loses its strike minus the net premium you took in, times 100 shares per contract.
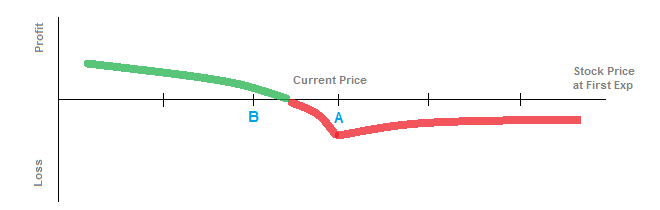
The reverse diagonal our Strategy Benchmarks track, valued at the first (near) expiration. Strike A: near-dated put bought. Strike B: later-dated put sold.
What you can find out
How do you profit from a diagonal put spread?
From time decay and a modest fall toward the short strike. The nearer put you sold loses value faster than the later put you own; if the stock is at or a little above the short strike when the near put expires, the short put expires worthless and your later put still has value. See the worked example
What is the most a diagonal put spread can lose?
For the usual version, with the later put at the higher strike, the debit: $410 per spread in our example. The reverse version can lose much more once the near put expires, because the later short put is then uncovered.
Which version do Market Chameleon's tools use?
Option Strategy Benchmarks › Diagonal Put tracks the reverse version: buy the at-the-money put 30, 60 or 90 days out and sell a put 5% below the stock price at a later maturity of 60, 90 or 120 days. The Multi-Leg Trade Screener shows diagonals as they traded, in either direction. See SPY's diagonal put benchmark
Where can I see diagonal put spreads other traders put on?
On the Multi-Leg Trade Screener, pick Diagonal Put Spread in the Spread Type filter. In the Strike Direction filter, Ascending means the longer-dated leg has the higher strike, as in the usual put diagonal; Descending means it has the lower strike. Open the Multi-Leg Trade Screener
Where to find it
- Multi-Leg Trade Screener (Screeners › For Premium Users › Multi-Leg Trades): diagonal put spreads of 200 contracts or more traded on the report date, under Diagonal Put Spread in Spread Type (Put Diagonal Ratio Spread and Diagonal Double Put Spread are separate types). Strike Direction, Strike Sprd and the DTE Near and DTE Far Expiration filters narrow them down. The label describes the structure, not the side; % to Ask helps judge whether the spread was bought or sold.
- Option Strategy Benchmarks › Diagonal Put, on a stock's pages: what the reverse diagonal costs now for six pairs of maturities, its change, its 52-week average and where today's cost ranks in the past year, marked Debit or Credit.
- Not covered: the Options Backtester doesn't test diagonals, and Strategy Payout draws one expiration at a time.
Worked example
The stock is at $100. Buy the 90-day $100 put for $5.45 and sell the 30-day $95 put for $1.35: a debit of $4.10, or $410 per spread. Here is the spread 30 days later, when the short put expires, if implied volatility stays at 30%:
| Stock at near expiration | $95 put sold | $100 put bought (60 days left) | Spread value | Profit or loss per spread |
|---|---|---|---|---|
| $120 | $0 | about $0.35 | $0.35 | about −$375 |
| $110 | $0 | about $1.45 | $1.45 | about −$265 |
| $105 | $0 | about $2.65 | $2.65 | about −$145 |
| $100 | $0 | about $4.50 | $4.50 | about +$40 |
| $95 | $0 | about $7.20 | $7.20 | about +$310 |
| $90 | −$5.00 | about $10.70 | $5.70 | about +$160 |
The best result is with the stock at the $95 short strike. The trade breaks even a little above $100. On a deeper fall the spread is worth at least the $5 between the strikes, because the long put can be exercised for $100 minus the stock price, so it keeps a gain of at least $90. On a rise the loss approaches the $410 debit. A drop in implied volatility would lower every value in the long-put column.
Option values estimated with Black-Scholes at 30% implied volatility, a 4% interest rate and no dividends, rounded. An illustration of the math, not a trade idea. Commissions and fees are left out.
FAQ
- What is a diagonal put spread?
- Buying a put with a later expiration and selling a put with a nearer expiration at a lower strike, usually for a net debit. It is the put-side mirror of the diagonal call spread.
- How is it different from a calendar put spread?
- A calendar uses one strike for both expirations. A diagonal sells the nearer put at a lower strike, which gives it room to gain as the stock falls toward that strike.
- What happens when the near-term put expires?
- If it expires worthless, you still own the later put: sell it, hold it as protection, or sell another near-term put against it. If it is in the money, buy it back or expect assignment, which leaves you with 100 shares per contract bought at its strike.
- Can the short put be assigned early?
- Yes, for American-style options such as most US stock and ETF options, most often when it is deep in the money with little time value left.
- How does implied volatility affect a diagonal put spread?
- The usual diagonal gains when implied volatility rises, because the later put has more vega than the near one, and loses when it falls.
Related
Option Strategies Diagonal Call Spread Calendar Spread Screener Debit Put SpreadTerms on this page
Calendar spread Vega Time value AssignmentMarket Chameleon provides data, not investment advice.