

Risk Reversal
A bullish risk reversal buys an out-of-the-money call and sells an out-of-the-money put, often for little or no net cost. Gains above the call strike have no cap; losses below the put strike are large but capped, since a stock can only fall to zero.
What is a risk reversal?
A risk reversal pairs two out-of-the-money options of the same expiration. The bullish (long) risk reversal buys a call above the stock price and sells a put below it; the bearish (short) version does the opposite. The premium from the option sold pays for some, all, or more than all of the option bought, so the position can cost little or nothing up front.
Outside the strikes it behaves like owning the stock: above the call strike it gains as the stock rises, below the put strike it loses as the stock falls. Between the strikes, at expiration, it is flat at whatever net premium was paid or received. Traders use it to take a bullish position with little cash spent on premium, accepting the obligation to buy the stock at the put strike if it falls. This guide covers the bullish version: buy the call at strike B, sell the put at strike A.
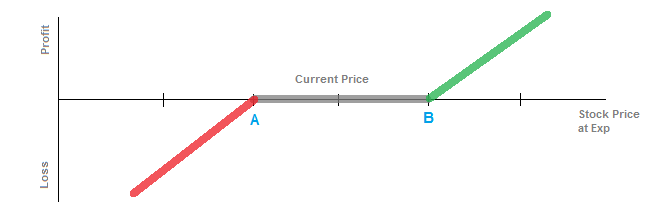
Payoff at expiration, drawn for zero net cost. Strike A: put sold. Strike B: call bought.
How a risk reversal pays off
- Net cost. Call premium paid minus put premium received. If the call costs more, it is a net debit; if the put brings in more, a net credit.
- Above the call strike (B). Gains $1 a share for each $1 the stock is above B, less a net debit or plus a net credit. There is no cap on the gain.
- Between the strikes. Both options expire worthless: you keep the net credit or lose the net debit.
- Below the put strike (A). Loses $1 a share for each $1 the stock is below A, like owning the stock from A down. If the stock went to zero, the loss would be A a share, plus a net debit or minus a net credit. Large, but capped.
- Per contract. A standard US stock option covers 100 shares, so multiply the per-share amounts by 100.
| At expiration | Net credit C | Zero cost | Net debit D |
|---|---|---|---|
| Breakeven | A − C | Anywhere between A and B | B + D |
| Between the strikes | +C | 0 | −D |
| Most it can lose (stock at $0) | (A − C) × 100 | A × 100 | (A + D) × 100 |
| Most it can gain | No cap | No cap | No cap |
The short put: margin and assignment
- An obligation to buy. Each put sold obliges you to buy 100 shares at strike A if it is assigned. The call you bought doesn't protect against a fall.
- Margin. Brokers require margin, or cash set aside, to hold a short put, and the requirement can rise as the stock falls.
- Early assignment. Most US stock and ETF options are American-style, so the put can be assigned on any day before expiration, most often when it is deep in the money with little time value left. You would then own the shares, and still hold the call.
What you can find out
What is the most a risk reversal can lose?
Below the put strike it loses like stock. If the stock went to zero, the loss would be the put strike plus any net debit, or minus any net credit, times 100 shares per contract: large, but not unlimited. Selling the $95 put in a zero-cost risk reversal could lose up to $9,500 per contract. See the payoff table
Where does a risk reversal break even?
At expiration: for a net debit, the call strike plus the debit; for a net credit, the put strike minus the credit. At zero cost, it breaks even anywhere between the two strikes, makes money above the call strike and loses below the put strike. Draw one with SPY's option prices
Is a risk reversal the same as synthetic long stock?
Not quite. With the call and the put at the same strike and expiration, buying the call and selling the put is synthetic long stock: it moves dollar for dollar with the stock at every price. A risk reversal uses two different strikes, so it is flat between them and acts like stock only outside them. Read about synthetic stock positions
Why can a risk reversal cost nothing, or even pay a credit?
Because the put sold can be worth as much as the call bought, or more. Volatility skew is one reason: out-of-the-money puts below the stock price usually trade at higher implied volatility than out-of-the-money calls above it, so the put can bring in enough to pay for the call. Read about volatility skew
Where can I see risk reversals other traders put on?
Risk reversals traded as one order show on the Multi-Leg Trade Screener: pick Risk Reversal in the Spread Type filter on a day one traded. Ones put on as two separate trades show on Legged Spreads, where long risk reversals count as bullish and short ones as bearish. Open the Multi-Leg Trade Screener
Where to find it
- Strategy Payout, in a stock's Options menu: choose the Risk Reversal preset to draw the payoff at expiration with the stock's option prices (the mid-point of the bid and ask, from delayed data). For example /Overview/SPY/StrategyPayout/.
- Strategy Benchmarks › Risk Reversal: what a risk reversal that buys a call 5% above the stock price and sells a put 5% below costs now, 30, 60 and 90 days out, against its 52-week average and where today's cost ranks in the past year. For example /Overview/SPY/Option-Strategy-Benchmarks/Risk-Reversal/.
- Traders' risk reversals: the Multi-Leg Trade Screener (one order) and Legged Spreads (two separate trades).
Payoff at expiration: an example
The stock is at $100. Buy the $105 call and sell the $95 put of the same expiration, for zero net cost. At expiration:
| Stock at expiration | $105 call bought | $95 put sold | Per share | Per contract |
|---|---|---|---|---|
| $0 | $0 | −$95 | −$95 | −$9,500 |
| $80 | $0 | −$15 | −$15 | −$1,500 |
| $95 to $105 | $0 | $0 | $0 | $0 |
| $120 | +$15 | $0 | +$15 | +$1,500 |
Paid a net debit? Subtract it from every row, and the breakeven moves up to $105 plus the debit. Took in a net credit? Add it to every row, and the breakeven moves down to $95 minus the credit.
An illustration of the math with round numbers, not a trade idea. Commissions and fees are left out.
FAQ
- What is a bearish (short) risk reversal?
- The mirror image: buy an out-of-the-money put and sell an out-of-the-money call. It gains as the stock falls below the put strike and loses as the stock rises above the call strike. A stock can keep rising, so the short call's loss has no cap.
- Can the short put be assigned early?
- Yes, for American-style options such as most US stock and ETF options: the put can be assigned on any day before expiration, most often when it is deep in the money with little time value left. You would then buy 100 shares per contract at the put strike.
- Does a risk reversal need margin?
- The short put does: brokers require margin, or cash set aside to buy the shares, and the requirement can rise if the stock falls. The rules vary by broker and account.
- What does risk reversal mean as a volatility quote?
- Traders also use the term for a skew measure: the implied volatility of a 25-delta call minus that of a 25-delta put of the same expiration. A stock's Skew page on Market Chameleon shows the same gap the other way round, as 25-delta put minus call.
Related
Option Strategies Synthetic Stock Positions Option Volatility Skew Legged Option SpreadsTerms on this page
Out of the money (OTM) Volatility skew Synthetic long stock AssignmentMarket Chameleon provides data, not investment advice.